Introduction
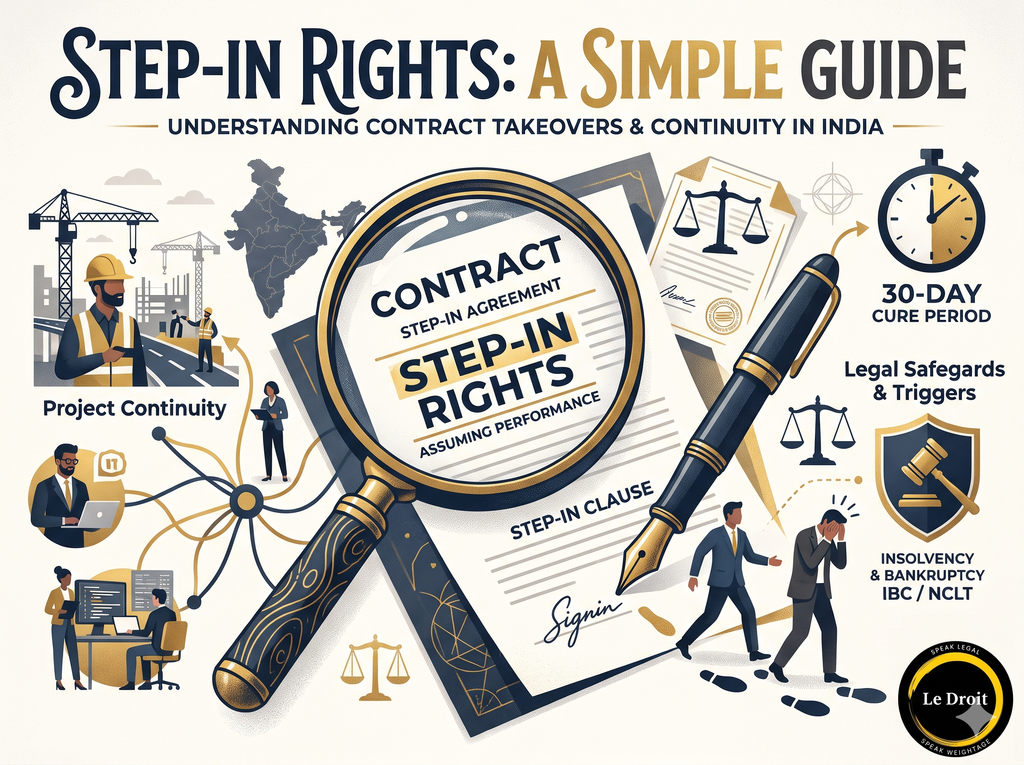
A step-in right allows a third party, commonly a lender, a project client, or a joint venture partner, to take over the performance of a contract from the original contracting party, usually when that party defaults, becomes insolvent, or is unable to continue performing.
In plain words: if a contractor building a highway or running a critical IT system runs into financial trouble and can’t finish the job, a step-in right lets the lender financing the project, or the client who needs the job done, step into the contractor’s shoes and keep the project moving, instead of the whole arrangement collapsing.
Step-in rights occupy an unusual place among contractual remedies: most remedies (damages, termination) deal with the consequences of a failed relationship after the fact, whereas a step-in right is designed to prevent the failure from becoming terminal in the first place. For large infrastructure projects especially, where termination and re-procurement can take years and destroy enormous value, the ability to keep the underlying project alive by substituting a new performing party is often far more valuable to all stakeholders than any amount of damages could be.
Legal Foundation: What Does Indian Law Say About It?
Step-in rights are purely contractual, created under the Indian Contract Act, 1872, and there is no dedicated statute that creates or governs them directly. They are most developed in project finance and infrastructure contracts, where a lender financing a project typically negotiates a separate direct agreement (also called a tripartite or step-in agreement) with the project company and the key counterparties, such as the EPC contractor or the off-taker, giving the lender the contractual right to step in and complete or novate the underlying contract if the borrower defaults.
The most important Indian legal wrinkle to flag is the interaction between step-in rights and the Insolvency and Bankruptcy Code, 2016 (IBC). Once a company enters the Corporate Insolvency Resolution Process (CIRP), Section 14 of the IBC imposes a moratorium that bars, among other things, the institution or continuation of proceedings against the corporate debtor and the enforcement of certain security interests. Courts and the NCLT have held that contractual step-in or termination rights that a counterparty might otherwise exercise on insolvency can be suspended or restricted once the moratorium kicks in, which is a critical drafting consideration: a step-in right drafted assuming it can be freely exercised on “any insolvency event” may not actually be exercisable the moment it is needed most, once CIRP has formally commenced.
This timing problem is worth dwelling on because it fundamentally shapes how sophisticated lenders approach step-in rights in practice. Rather than treating the step-in right as something to be exercised only once a default has become undeniable, well-advised lenders build early-warning mechanisms into their financing documents, financial covenants, reporting obligations, independent engineer oversight, that are designed to surface signs of distress well before a formal insolvency filing. The goal is to give the lender a realistic window to exercise the step-in right while it remains contractually and practically available, rather than discovering only after a CIRP petition has been admitted that the moratorium has foreclosed the very remedy the step-in right was meant to provide.
It is also worth noting the Supreme Court’s broader jurisprudence on the IBC moratorium’s scope, which has generally taken an expansive view of what counts as a “proceeding” against the corporate debtor for Section 14 purposes, while leaving some room for essential supplies and certain categories of continuing performance to proceed during CIRP where necessary to preserve the entity as a going concern. This nuance matters for step-in drafting: a step-in exercised specifically to keep a project running, rather than to assert a claim against the insolvent party, may in some circumstances be more consistent with the IBC’s own going-concern objectives, though this remains a fact-specific determination that any lender or client should take specific legal advice on before assuming a step-in can proceed despite an ongoing moratorium.
Practical Relevance: Why Does It Matter in Actual Contracts?
Step-in rights are central to contracts where continuity of performance is business-critical:
- Project finance and infrastructure contracts (roads, power, ports), where lenders need assurance a project doesn’t grind to a halt if the borrower defaults.
- EPC (engineering, procurement, construction) contracts, where the employer wants the ability to bring in a replacement contractor without terminating the underlying contract and starting from zero.
- Outsourcing and managed services agreements, where a client needs a fallback if the service provider can’t continue delivering a critical function.
- Joint ventures, where one partner’s operational default could otherwise jeopardise the entire venture.
Without a properly negotiated step-in right, the only options when a counterparty fails are usually termination (which can be slow, costly, and disruptive) or simply living with non-performance, neither of which protects a lender’s security or a client’s operational continuity.
A few further contexts are worth adding. Public-private partnership (PPP) concessions, where the government authority typically negotiates its own step-in right directly into the concession agreement, allowing it to take over or appoint a substitute operator if a critical public service, such as a toll road or a water utility, is at risk of disruption. Long-term defence and critical supply contracts, where national security or public safety considerations make continuity of supply a government priority independent of the commercial dispute between the contracting parties. Technology and data-hosting agreements for critical infrastructure, where a client may negotiate a step-in right specifically covering access to source code, infrastructure credentials, and operational runbooks, recognising that a service provider’s financial distress could otherwise leave the client unable to access or operate systems it fundamentally depends on.
Across all of these, the shared concern is the same: some relationships are too operationally important to be allowed to simply collapse when one party runs into trouble, and a step-in right is the mechanism that converts that shared concern into an enforceable, pre-planned solution.
Practical Application: How Is It Drafted or Used?
A workable step-in clause defines the specific trigger events, the process for notifying the defaulting party, the scope of what the stepping-in party takes over, and crucially, how liabilities are allocated during and after the step-in period.
A typical clause looks like this:
“Step-In Right. If Contractor commits a material default under this Agreement that remains uncured for thirty (30) days after written notice, or becomes subject to insolvency proceedings, Client (or Client’s lender, pursuant to a separate direct agreement) may, by written notice, step into Contractor’s role and assume performance of the Deliverables, either directly or through a replacement contractor, without terminating this Agreement. Contractor shall provide reasonable cooperation, including access to project documentation, sub-contracts, and personnel, to facilitate an orderly step-in, subject at all times to any applicable moratorium or other restriction under the Insolvency and Bankruptcy Code, 2016.”
When drafting or reviewing this clause, make sure it:
- Defines the trigger events precisely, material default, insolvency, abandonment of the project, rather than a vague “unable to perform” standard that invites disputes.
- Specifies a cure period before step-in can be exercised, so the right isn’t used as a hair-trigger takeover mechanism for minor or curable issues.
- Addresses cooperation obligations, handover of documents, sub-contracts, site access, personnel, since a step-in right is of limited use if the defaulting party can simply obstruct the handover.
- Allocates liability clearly between the original party and the party stepping in, especially for obligations and defects that straddle the step-in date.
- Expressly acknowledges the IBC moratorium and similar statutory restrictions, so the clause doesn’t promise an unconditional right that may not survive the counterparty’s insolvency process.
A few further drafting points are worth building into this checklist:
- Specify the duration and scope of the step-in period explicitly. Is the stepping-in party expected to complete the entire remaining contract, or only to bridge a temporary gap until a permanent solution (such as a novation to a replacement contractor) can be arranged? These are very different operational and liability propositions, and the clause should say which applies.
- Address payment obligations during the step-in period. Who pays the replacement contractor or the costs of the stepping-in party’s own performance during this period, and is the original defaulting party still entitled to receive any payments that would otherwise have been due to it, or are those redirected?
- Clarify whether the step-in right can be exercised more than once, or whether it is a one-time remedy. In long, complex projects, more than one default event may occur over the life of the contract, and the clause should specify whether step-in remains available for subsequent defaults.
- Consider requiring notice to other affected stakeholders, such as sub-contractors, insurers, or regulatory authorities, where their cooperation or consent may be necessary for an orderly step-in to actually function in practice.
- Build in an exit mechanism from the step-in arrangement itself. Once the underlying issue is resolved, or a permanent replacement is in place, the clause should specify how and when the stepping-in party’s temporary role ends, and whether the original party (if it recovers) has any right to resume performance.
Common Drafting Mistakes to Avoid
- Drafting the trigger as a vague “unable to perform” standard, which invites disputes about whether a temporary, recoverable setback actually justifies a full step-in, as opposed to a genuine, sustained default.
- Omitting a cure period entirely, turning the step-in right into a hair-trigger mechanism that a counterparty can invoke over a minor, quickly fixable issue, straining the relationship unnecessarily.
- Failing to address cooperation obligations in enough detail, leaving the defaulting party able to passively obstruct a handover by simply not responding to requests for documents, access, or personnel transfer.
- Not allocating liability clearly for obligations and defects that straddle the step-in date, creating disputes about who is responsible for a problem that originated before step-in but manifested after it.
- Assuming the step-in right survives automatically once the counterparty enters insolvency proceedings, without expressly addressing the Section 14 IBC moratorium, which can suspend exactly the self-help remedy the clause was meant to provide at the moment it matters most.
- Drafting a step-in right for a lender without a properly executed, standalone direct agreement with the project company and key counterparties, leaving the lender’s practical ability to actually exercise the right dependent on cooperation it has no separate contractual basis to compel.
A Worked Example
A mid-sized EPC contractor, “Nirman Infraworks,” is engaged to build a water treatment plant for a municipal client, with the project financed by a consortium of lenders who have negotiated a separate direct agreement giving them step-in rights if Nirman defaults. Eighteen months into the two-year project, Nirman’s finances deteriorate sharply due to unrelated cost overruns on another project, and work on the water treatment plant stalls for six weeks with no clear explanation to the client or the lenders.
The lenders, monitoring the project closely under their direct agreement, issue a formal notice of material default, and after the thirty-day cure period passes without meaningful progress, exercise their step-in right. Because the direct agreement clearly defined the trigger, required Nirman’s cooperation in handing over site access, sub-contractor agreements, and project documentation, the lenders are able to bring in a replacement contractor within three weeks and resume construction with minimal further delay to the municipal client.
Six months later, Nirman Infraworks formally enters insolvency proceedings. Because the lenders had already exercised their step-in right and completed the handover before the Section 14 IBC moratorium took effect, their intervention wasn’t caught up in the moratorium’s restrictions, a timing outcome the lenders’ legal team had specifically planned for by moving decisively the moment the cure period expired, rather than waiting and risking losing the practical ability to step in once insolvency proceedings formally began.
This sequence of events underscores a point that is easy to underappreciate in the abstract but becomes very concrete in practice: the value of a step-in right is not just a function of how it is drafted, but of how closely the party holding it monitors the counterparty’s financial condition and how decisively it acts once the contractual trigger has actually been satisfied. A perfectly drafted step-in clause exercised too late, after insolvency proceedings have already commenced, can end up providing far less practical protection than a more modestly drafted clause exercised promptly and decisively while it remained fully available.
Business Connection: How Does It Relate to Real-World Legal Operations?
Step-in rights are the kind of clause that matters enormously, but rarely, and when it does matter, there usually isn’t time to carefully re-read the contract for the first time. Legal and risk teams managing a portfolio of project, EPC, or outsourcing contracts need to know in advance which agreements carry a step-in mechanism, what triggers it, and what notice and cure periods apply.
Contract lifecycle management tools support this by flagging step-in provisions across the contract portfolio, tracking any linked default or cure-period clocks once a dispute or performance issue arises, and surfacing the clause immediately when it’s needed rather than requiring someone to locate and interpret it under pressure.
For lenders and project sponsors specifically, early-warning monitoring of a counterparty’s financial health, tied directly to the contractual step-in trigger, can be the difference between stepping in while the right is still freely exercisable and finding that an insolvency filing has already complicated the picture.
Recording a detailed, contemporaneous account of the events leading up to a step-in decision also matters enormously if the step-in is later challenged, whether by the defaulting counterparty, its other creditors, or in subsequent insolvency proceedings, which is another reason structured tracking of defaults, notices, and cure periods is worth more than informal, ad hoc record-keeping once a real dispute has already begun.
This record-keeping discipline matters even more once a step-in has actually occurred, since the stepping-in party will often need to demonstrate, potentially years later in insolvency proceedings or a dispute with the original contractor’s other creditors, exactly when the default occurred, when notice was given, when the cure period expired, and when the step-in right was exercised. A clear, contemporaneous paper trail built into the contract management process from the outset is far more persuasive than a reconstructed timeline assembled under the pressure of subsequent litigation.
Call to Action: Where Can You Learn More?
Clauses like this one don’t sit in isolation, they sit inside a much larger body of corporate and commercial law. If you want a structured, foundational understanding of how Indian company law shapes the contracts, governance, and compliance work you do every day, LeDroit India’s Company Laws in India Certificate Course is a good next step.