
Introduction
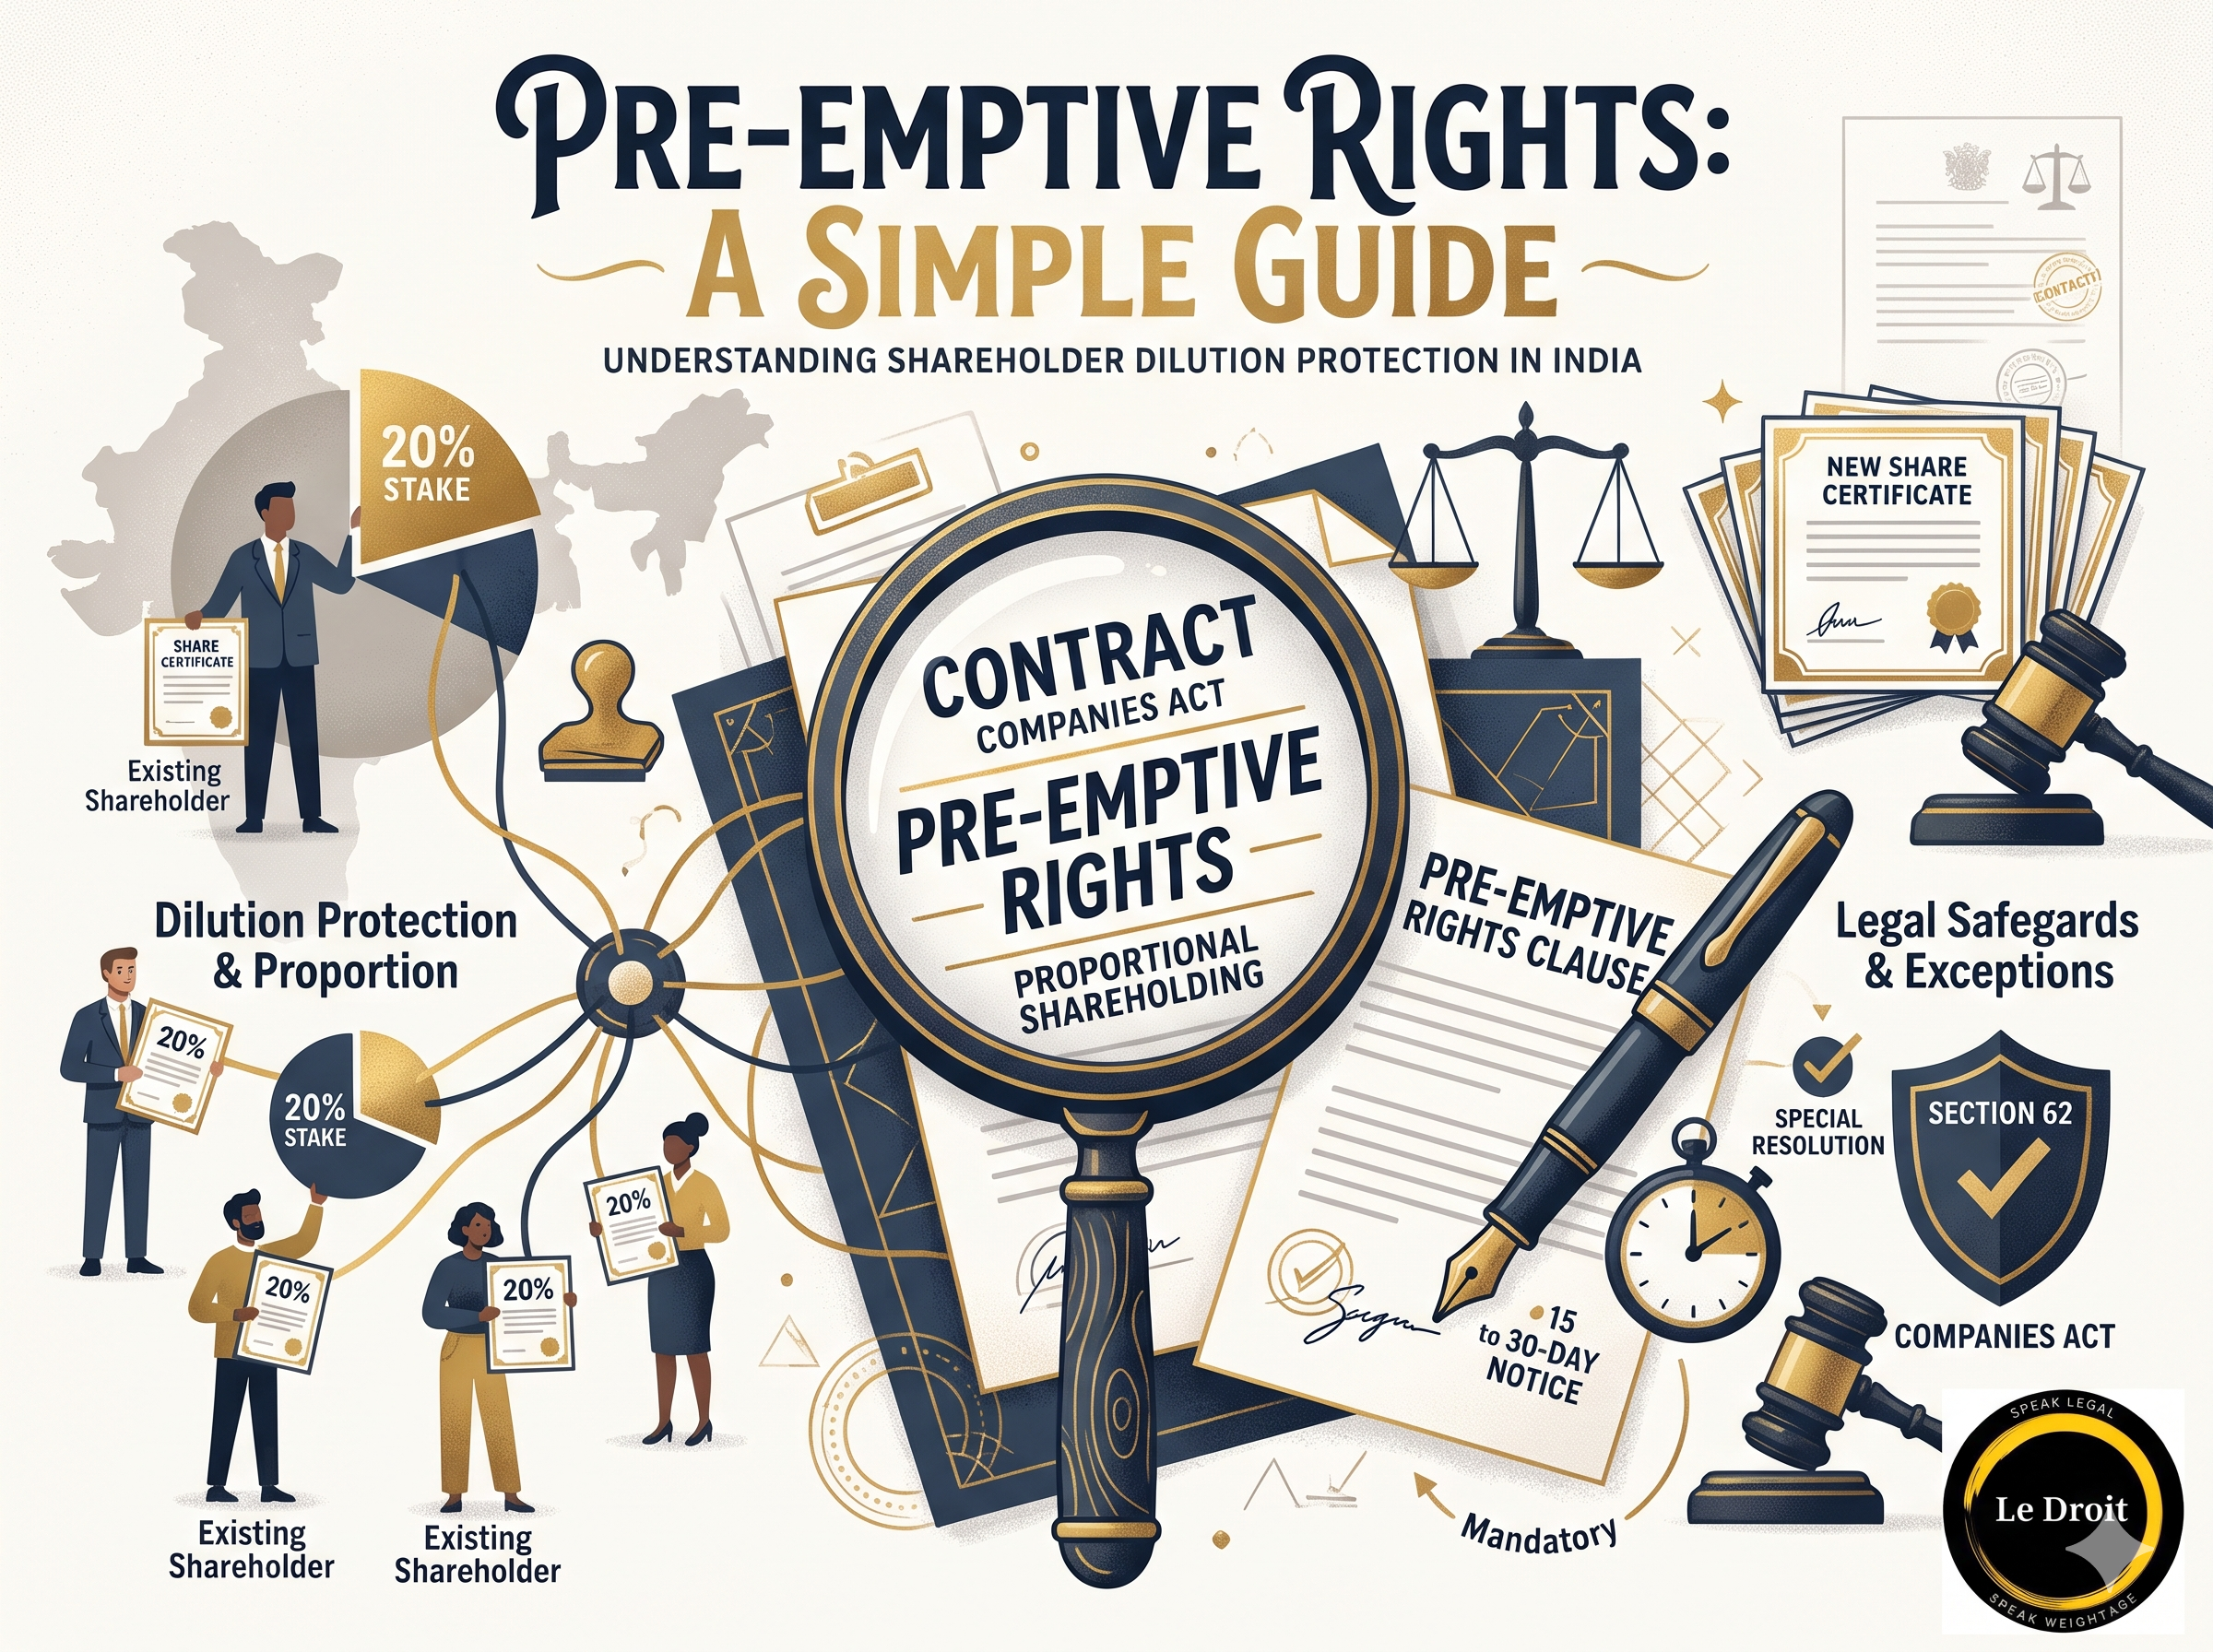
A pre-emptive right gives existing shareholders the first opportunity to subscribe to new shares a company issues, in proportion to their existing shareholding, before those shares can be offered to anyone outside the company.
In plain words: if a company wants to raise fresh capital by issuing new shares, existing shareholders get first right to buy enough of the new shares to maintain their current percentage ownership, so their stake isn’t diluted without their consent.
Pre-emptive rights stand apart from most of the other rights covered in this series because, unlike a ROFR or a drag-along right, they are not purely a creature of private contract. The Indian legislature decided this particular protection was important enough to make mandatory by default, which is precisely why getting the Section 62 process right, or properly disapplying it, is treated with such seriousness by company secretaries, legal teams, and due diligence counsel in every subsequent transaction.
Legal Foundation: What Does Indian Law Say About It?
Unlike most of the rights in this series, pre-emptive rights in India are directly codified in statute. Section 62(1)(a) of the Companies Act, 2013 requires that where a company proposes to increase its subscribed share capital by issuing further shares, those shares must first be offered to existing equity shareholders in proportion to their paid-up share capital.
The statute builds in specific procedural safeguards:
- Notice period: the offer must be made by notice specifying the number of shares offered, and must remain open for not less than fifteen days and not more than thirty days from the date of offer (a private company can shorten this with the consent of 90% of shareholders).
- Right to renounce: shareholders have the right to renounce the shares offered to them in favour of another person, unless the articles restrict this.
- Deemed declined: if no reply is received within the notice period, the offer is deemed to have been declined, allowing the company to allot the shares elsewhere, typically to the board, at terms not less favourable than those offered to shareholders.
This statutory pre-emptive right can be disapplied by a special resolution under Section 62(1)(c) (a preferential allotment), which is how companies issue shares to new investors, ESOP pools, or in M&A transactions without first running the Section 62 rights-issue process. The Supreme Court’s decision in Needle Industries (India) Ltd. v. Needle Industries Newey (India) Holding Ltd. (1981) remains a key authority on how pre-emptive rights interact with allegations of oppression and mismanagement when a board issues shares in a manner that dilutes a minority without a genuine business justification.
It is worth unpacking why the Needle Industries line of reasoning continues to matter so much in practice. The case establishes that a board’s decision to issue shares in a way that dilutes a minority shareholder is not automatically oppressive merely because dilution occurs, courts look at whether there was a genuine business justification (such as a real need for capital) and whether the process followed was fair, including whether minority shareholders were given a genuine opportunity to participate. This means a company that follows the Section 62 process correctly, with proper notice and a real opportunity to subscribe, is in a much stronger position to defend an allotment against a later oppression claim, even if the ultimate commercial effect is still some dilution of a shareholder who chose not to, or could not afford to, participate.
It is also worth flagging the interaction between Section 62 and the pricing requirements that apply to preferential allotments under Section 62(1)(c), read with the relevant rules under the Companies (Share Capital and Debentures) Rules, 2014. A preferential allotment disapplying pre-emptive rights must generally be priced using a valuation methodology prescribed by the rules (or, for listed companies, SEBI’s ICDR Regulations), rather than at the board’s unconstrained discretion, which is an additional safeguard layered on top of the special resolution requirement itself, specifically to prevent minority dilution at an artificially low price even where the pre-emptive right has been validly disapplied.
Practical Relevance: Why Does It Matter in Actual Contracts?
Pre-emptive rights matter in:
- Every fresh issuance of shares by an Indian company, since Section 62(1)(a) applies by default unless validly disapplied.
- Shareholders’ agreements, which often layer additional contractual pre-emptive rights on top of the statutory ones, sometimes with different proportions, notice periods, or triggers (including on transfers, not just new issuances).
- Startup fundraising, where founders and early investors need to understand whether, and by how much, a new funding round will dilute them, and whether they have the right (and the capital) to participate and maintain their percentage.
Getting this wrong, by issuing shares without properly following Section 62, or without a validly passed special resolution disapplying it, can expose an allotment to challenge and create serious downstream complications in future fundraising or M&A due diligence.
A few additional contexts are worth highlighting. Rights issues by listed companies, where the Section 62 process intersects with SEBI’s ICDR Regulations governing rights issue timelines, disclosures, and pricing, adding an additional regulatory layer on top of the Companies Act requirements. Employee stock option pools, where companies must carefully structure ESOP allotments, which are themselves typically carved out from pre-emptive rights by design, to ensure the carve-out is properly documented and doesn’t inadvertently create a pre-emptive rights violation for shares issued on exercise of options. Convertible instruments, such as compulsorily convertible preference shares or convertible notes, where the pre-emptive rights analysis needs to account for the dilution that will occur on conversion, not just at the point of initial issuance, since existing shareholders’ practical dilution exposure is really determined by the fully-diluted capital structure, not simply the shares outstanding at any given moment.
Across all of these situations, the statutory default plays the same protective role: ensuring that existing shareholders are not diluted without either a genuine opportunity to maintain their position, or a properly authorised, transparent process for deciding that dilution is appropriate in the circumstances.
Practical Application: How Is It Drafted or Used?
Where a shareholders’ agreement supplements the statutory right, the clause typically restates the proportional offer mechanism, sets contract-specific notice periods, and clarifies what happens if a shareholder doesn’t subscribe.
A typical clause looks like this:
“Pre-Emptive Rights. If the Company proposes to issue any new equity shares, the Company shall first offer such shares to each Shareholder in proportion to their then-current shareholding, by written notice specifying the number of shares, the price, and the subscription period of not less than fifteen (15) days. A Shareholder who does not subscribe for its full pro-rata entitlement within such period shall be deemed to have waived its pre-emptive right with respect to the unsubscribed shares, which the Company may then offer to other Shareholders or third parties on terms no more favourable than those offered under this clause.”
When drafting or reviewing this clause, make sure it:
- Aligns the notice period with Section 62’s statutory minimum of fifteen days, to avoid a contractual clause that inadvertently falls short of the statutory requirement.
- States the proportion clearly, based on current shareholding, not voting rights or a different metric, to avoid disputes over how much each shareholder is entitled to subscribe for.
- Addresses over-subscription, where more than one shareholder wants to pick up shares others declined, and how that excess is allocated.
- Confirms whether the right applies only to new issuances or also to secondary transfers, since the two are often confused but trigger different legal regimes (Section 62 versus a contractual ROFR).
- Records the special resolution process clearly whenever the right is to be validly disapplied for a specific allotment under Section 62(1)(c), since skipping this step is a common and serious compliance gap.
A few additional drafting considerations are worth building into this checklist:
- Address the fully-diluted calculation basis explicitly, particularly where the company has outstanding convertible instruments or an ESOP pool. A clause that calculates pro-rata entitlement only on currently issued shares, ignoring instruments that will convert into shares later, may understate a shareholder’s true dilution exposure and lead to disputes when conversions eventually occur.
- Specify the valuation methodology that will apply if pre-emptive rights are disapplied for a preferential allotment, cross-referencing the applicable rules under the Companies (Share Capital and Debentures) Rules, 2014, so that pricing disputes don’t surface after the special resolution has already been passed.
- Clarify the interaction between contractual and statutory notice periods where a shareholders’ agreement specifies a longer period than the statutory fifteen days, making clear which period actually governs and avoiding a scenario where the company complies with one but not the other.
- Build in a standard carve-out for ESOP pool issuances from the start, rather than negotiating a waiver each time options are exercised, since a properly scoped standing carve-out in the shareholders’ agreement avoids repeated, unnecessary special resolutions for routine, already-anticipated dilution.
- Maintain a clear process for proof of delivery of pre-emptive rights notices, including registered post, email with read receipts, or another verifiable method, since a shareholder’s later claim of non-receipt can be difficult to rebut without contemporaneous evidence that the notice was actually sent and received within the statutory window.
Common Drafting Mistakes to Avoid
- Issuing new shares to a new investor without first completing the Section 62(1)(a) rights-issue process or validly passing the Section 62(1)(c) special resolution to disapply it, a defect that can render the allotment challengeable long after the shares have been issued.
- Sending the pre-emptive rights notice with a subscription window shorter than the statutory fifteen-day minimum, inadvertently falling foul of Section 62 even where the company genuinely intended to comply.
- Failing to specify how over-subscription is handled when more than one existing shareholder wants to pick up shares others declined, leaving an ad hoc, potentially disputed allocation process.
- Confusing pre-emptive rights on new issuances with a Right of First Refusal on secondary transfers, applying the wrong notice period or process because the two distinct rights were not clearly separated in the drafting.
- Not documenting the special resolution and shareholder consents properly when pre-emptive rights are waived for a specific strategic allotment, creating an evidentiary gap that surfaces precisely when a disgruntled shareholder later challenges the allotment.
- Assuming all shareholders have been validly notified without maintaining proof of delivery, which becomes a significant problem if a shareholder later claims they never received the offer within the statutory window.
A Worked Example
A fast-growing edtech company, “ShikshaSetu,” plans to raise a new funding round by issuing shares to a venture capital fund. Several existing angel investors, who collectively hold 20% of the company, are not part of this new round. The company’s finance team, eager to close the deal quickly, sends term sheets to the VC fund and begins preparing allotment paperwork without first running the Section 62(1)(a) rights-issue process for the existing shareholders.
The company’s legal counsel catches the gap just before the board meeting to approve the allotment, and advises that unless the pre-emptive rights are either properly offered to existing shareholders with a valid notice period, or formally disapplied through a special resolution under Section 62(1)(c), the allotment risks being challenged later as improperly authorised. The company quickly convenes a shareholder vote, secures the required special resolution with more than three-fourths approval, and documents the waiver properly before proceeding.
Had this gap gone unnoticed until after the funding round closed, ShikshaSetu would have faced a materially more difficult, and more public, problem: unwinding or ratifying a completed allotment that an aggrieved angel investor could challenge as having been issued in breach of their statutory pre-emptive rights, exactly the kind of defect that due diligence teams in a future funding round or acquisition are specifically trained to look for.
This example is a useful illustration of a broader pattern: compliance defects around pre-emptive rights are rarely the product of a company deliberately trying to disadvantage its minority shareholders. Far more often, they arise from deal teams moving quickly under commercial pressure and simply overlooking a procedural step that, while statutorily mandatory, is easy to treat as an afterthought when the commercial terms of a funding round are the primary focus of everyone’s attention.
Business Connection: How Does It Relate to Real-World Legal Operations?
Every fundraising round is, procedurally, a compliance event: notices have to go out, timelines have to be honoured, and company secretarial filings have to follow. Missing a pre-emptive rights notice, or getting the subscription window wrong, can create a defect that surfaces much later, often during due diligence for the next round or an eventual exit.
This is a natural checklist-and-deadline problem for contract lifecycle management and compliance tracking tools: generating the required notices automatically when a new allotment is proposed, tracking the statutory and contractual timelines in parallel, and keeping a clean audit trail showing every shareholder was properly offered their pro-rata entitlement before any shares went to an outside investor.
For companies raising multiple funding rounds over several years, this compliance trail becomes an increasingly important due diligence asset in its own right, a clean, well-documented history of every pre-emptive rights notice and waiver materially speeds up legal review in a future transaction, compared to reconstructing that history retroactively from scattered emails and board minutes.
Company secretaries and legal teams working together on allotments also benefit from a shared, structured checklist that ties the Section 62 notice period directly to each proposed issuance, so the question of whether existing shareholders were properly offered their entitlement is answered definitively by the record, rather than becoming a matter of recollection months or years after the allotment was completed.
This kind of structured tracking becomes especially valuable at the moment a company begins preparing for an acquisition or a significant new funding round, when buyer or investor due diligence will almost certainly include a specific review of every historical share allotment for Section 62 compliance. A company that can produce a clean, well-organised record of every pre-emptive rights notice, subscription response, and waiver resolution across its entire fundraising history meaningfully shortens this diligence process, compared to one that must reconstruct the picture allotment by allotment under time pressure.
Call to Action: Where Can You Learn More?
Clauses like this one don’t sit in isolation, they sit inside a much larger body of corporate and commercial law. If you want a structured, foundational understanding of how Indian company law shapes the contracts, governance, and compliance work you do every day, LeDroit India’s Company Laws in India Certificate Course is a good next step.