Introduction
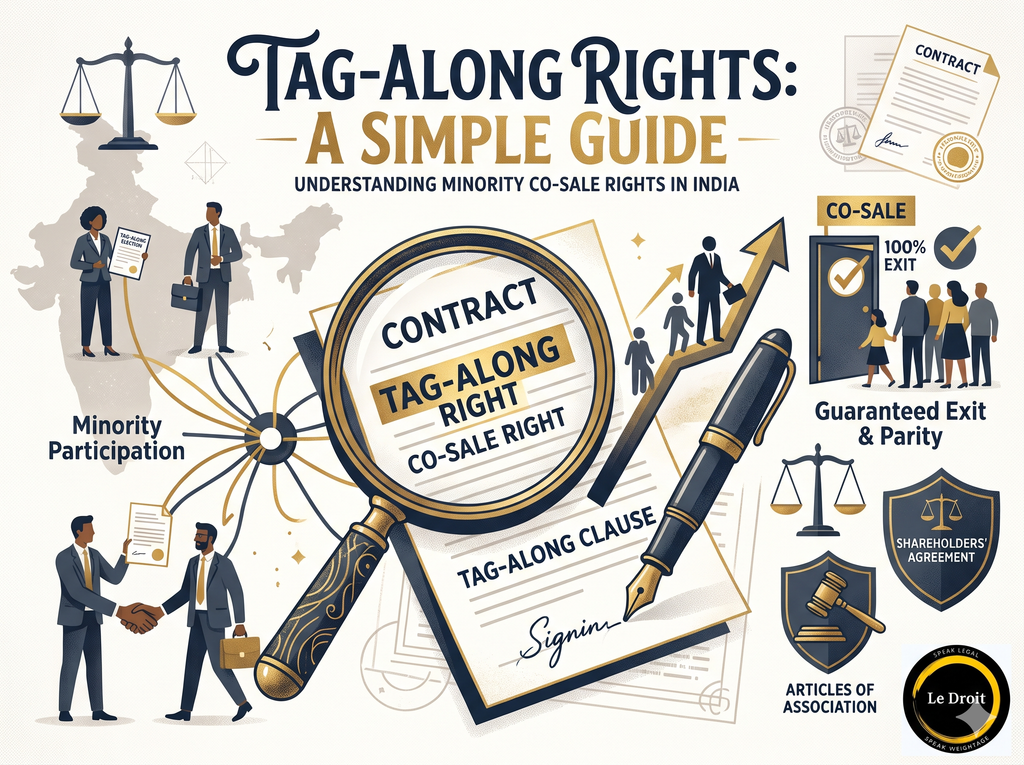
A tag-along right (also called a co-sale right) allows a minority shareholder to join in a sale of shares by a majority or controlling shareholder, selling their own shares alongside on the same price and terms, instead of being left behind as a minority partner of whoever the buyer turns out to be.
In plain words: it’s the mirror image of a drag-along right. Where drag-along lets the majority force the minority to sell, tag-along lets the minority choose to sell when the majority does.
The two rights are often negotiated together, and for good reason: a majority shareholder who wants drag-along protection (the ability to force a clean exit) will usually have to grant tag-along protection in return (the minority’s ability to exit on the same terms). This pairing reflects a basic fairness principle that runs through most shareholder agreements: whatever liquidity event the majority can trigger for itself, the minority should generally be able to share in, rather than being left exposed to whatever ownership structure the majority’s deal happens to produce.
Legal Foundation: What Does Indian Law Say About It?
Like drag-along rights, tag-along rights are a creature of contract, typically embedded in a shareholders’ agreement and, for maximum enforceability, mirrored in the company’s articles of association, relying on the same Messer Holdings line of authority and Section 2(68) of the Companies Act, 2013 that supports drag-along enforceability for private companies.
A practical legal mechanic that makes tag-along rights work in India is Section 58 of the Companies Act, 2013, which governs refusal to register a transfer. A properly drafted articles provision can make a majority shareholder’s proposed transfer conditional on the buyer also acquiring the tagging minority’s shares, and the company can decline to register a transfer that doesn’t comply, giving the tag-along right real teeth rather than being a purely personal contractual promise between shareholders.
Tag-along rights differ from drag-along rights in one important practical respect: they are optional for the holder, while drag-along is mandatory once triggered. This asymmetry means a tag-along clause needs to work even when only some minority shareholders choose to exercise it, the third-party buyer may end up negotiating to acquire a combined stake it didn’t originally plan for, and a well-drafted clause should make clear whether the buyer is obligated to accept this expanded transaction or can walk away if the combined stake exceeds what it is willing to purchase.
This optionality also has an interesting legal consequence worth understanding: because the tag-along right is a choice rather than an obligation, a minority shareholder who fails to exercise it within the stipulated window generally cannot later claim the right was violated simply because they changed their mind, or because the transaction turned out to be more favourable than they initially assessed. Courts enforcing contractual timelines in India have generally held parties to the notice and election periods they agreed to, which places real importance on minority shareholders (and their advisors) actually monitoring for transfer notices and responding within the window, rather than assuming the right remains available indefinitely.
Practical Relevance: Why Does It Matter in Actual Contracts?
Tag-along rights are especially important for minority investors and co-founders who have limited control but significant economic exposure:
- Venture capital and angel investors, who want the ability to exit alongside a founder or majority shareholder selling control, rather than being stuck as a minority investor in a company now controlled by an unknown buyer.
- Minority founders or early employees with meaningful equity, who want the same liquidity opportunity as the majority when a sale happens.
- Joint venture partners holding a minority stake, who don’t want to be left in business with whoever their partner chooses to sell to.
Without a tag-along right, a minority shareholder has no say in who their new co-shareholder is, and no guaranteed path to liquidity when the majority cashes out.
A few other situations where tag-along protection is especially valuable are worth adding. Family business successions, where a non-controlling family member holding a minority stake wants assurance that if the controlling branch of the family sells to an outsider, they are not left running a business alongside a stranger with no exit of their own. Strategic minority investments, where a corporate investor takes a small stake for strategic reasons (such as a supply relationship or technology access) but wants the ability to unwind that position cleanly if the majority owner changes. Secondary share sales in late-stage startups, where existing minority holders, including early employees who have exercised options, want the same opportunity as larger shareholders to achieve liquidity if a significant block of shares is being sold to a new investor.
Across all of these, the underlying protection is the same: tag-along rights exist to make sure a minority shareholder’s fate is not entirely determined by decisions made by someone else, without any say in the outcome for the minority’s own economic position.
Practical Application: How Is It Drafted or Used?
A tag-along clause needs to specify the trigger (any transfer above a threshold by a majority or founder shareholder), the proportion of the tagging shareholder’s stake they can include, and a clear notice and election timeline.
A typical clause looks like this:
“Tag-Along Right. If any Founder Shareholder proposes to transfer shares representing more than ten percent (10%) of the Company’s issued share capital to a third party, the Founder Shareholder shall give written notice to the other Shareholders, who may elect, within twenty-one (21) days, to include in such transfer a pro-rata portion of their own shares, on the same price and terms. The Founder Shareholder shall not complete the proposed transfer unless the third-party purchaser agrees to purchase the shares of all Shareholders who have validly exercised their tag-along right.”
When drafting or reviewing this clause, make sure it:
- Sets the trigger threshold clearly (any sale, or only sales above a stated percentage), so small routine transfers don’t unnecessarily activate the mechanism.
- Specifies whether tagging shareholders can include all or only a pro-rata portion of their holding, to avoid disputes about how much of the deal they’re entitled to join.
- Makes the restriction binding on the company through the articles, not just the SHA, so the company can refuse to register a non-compliant transfer.
- Builds in a realistic notice and election window, balanced against the practical reality that buyers want deal certainty and won’t wait indefinitely.
- Clarifies the interplay with any simultaneous drag-along right, so the two mechanisms don’t produce contradictory outcomes in the same transaction.
A few additional drafting points are worth adding to this checklist:
- Specify what happens if the buyer is unwilling to purchase the full, expanded stake once tagging shareholders have exercised their right. Some clauses allow the selling shareholder to proceed with a reduced sale of only their own shares if the buyer refuses to accept the larger combined stake, while others treat the buyer’s refusal as grounds for the selling shareholder to walk away from the deal entirely; the clause should specify which outcome applies.
- Address how warranties and indemnities are allocated among tagging shareholders. As with drag-along transactions, a buyer will typically want representations from all sellers, and a passive minority investor exercising a tag-along right may reasonably want a more limited warranty scope than the majority shareholder actually running the business.
- Clarify whether the tag-along right applies to transfers to affiliates or related parties of the majority shareholder, since a majority shareholder transferring shares to a related entity (rather than a genuine third party) may not trigger the same liquidity event that the tag-along right is meant to protect against, and the clause should say whether such transfers are carved out.
- Build in a mechanism for aggregating and communicating tag-along elections efficiently where there are many minority shareholders, since a transaction involving dozens of small shareholders each individually electing to tag along can become operationally unwieldy without a clear process for collecting and consolidating those elections.
- Consider the interaction with any transfer restrictions on the buyer’s side, particularly where the buyer itself has investors or co-shareholders who may need to approve the expanded purchase if the combined stake crosses certain thresholds under the buyer’s own governance documents.
Common Drafting Mistakes to Avoid
- Setting the tag-along trigger threshold so high that routine, smaller transfers escape it entirely, leaving minority shareholders exposed to exactly the kind of gradual, below-threshold exit by a majority shareholder the clause was meant to catch.
- Failing to require the third-party purchaser to buy all tagging shareholders’ shares as a condition of completing the deal, leaving tagging shareholders with a right that’s easy for a reluctant buyer to simply ignore.
- Leaving the pro-rata calculation method undefined, creating disputes about exactly how many shares each tagging shareholder is entitled to include when several minority holders want to tag along simultaneously.
- Not embedding the restriction in the articles of association, which allows the company to register a non-compliant transfer anyway, defeating the practical enforceability of the right.
- Setting an election window too short for minority shareholders to realistically assess a complex transaction and decide whether to tag along, particularly where the proposed deal terms are only partially disclosed.
- Treating tag-along and drag-along rights as entirely independent provisions without cross-referencing them, risking a scenario where both are triggered simultaneously by the same transaction with no clear priority between them.
A Worked Example
A founder holding 55% of a growing logistics-tech company, “RouteWise,” receives an attractive acquisition offer from a larger competitor for her entire stake. Two minority investors, holding 15% and 10% respectively, learn of the deal and want to exit alongside her rather than remain minority shareholders under new, unfamiliar ownership.
Because the shareholders’ agreement includes a properly drafted tag-along right, triggered at any transfer above 10% of share capital, with the third-party purchase conditioned on buying all tagging shareholders’ shares, both minority investors formally elect to tag along within the agreed twenty-one-day window. The acquirer, having built the tag-along mechanic into its own deal planning from the outset, simply expands its offer to cover the larger combined stake at the same per-share price, and the transaction closes smoothly with all three shareholders exiting together.
At a different company without a tag-along clause, a similar scenario played out very differently: a majority shareholder sold his controlling stake to an outside buyer, leaving the minority investors stuck as small shareholders in a company now controlled by an acquirer they’d never negotiated with and didn’t necessarily trust, with no contractual right to have joined the sale on the same terms.
The contrast between these two outcomes illustrates exactly why sophisticated investors insist on tag-along protection as a condition of investing in the first place. A minority stake without a tag-along right carries a meaningfully different risk profile than one with it, since the investor’s eventual liquidity becomes entirely dependent on either a company-wide exit event or the goodwill of whoever ends up controlling the company, neither of which is within the minority investor’s own control.
Business Connection: How Does It Relate to Real-World Legal Operations?
For companies with multiple funding rounds and a growing shareholder base, knowing exactly who holds a tag-along right, and under what threshold, becomes genuinely difficult to track manually once several SHAs with overlapping and sometimes inconsistent terms are in play.
Contract lifecycle management tools help here by consolidating shareholder-level rights across every agreement into one view, so that the moment a proposed share sale is on the table, legal and company secretarial teams can immediately identify who must be notified and given the opportunity to tag along, instead of manually cross-checking a stack of historical SHAs.
This matters especially for companies anticipating a future exit, since a buyer evaluating an acquisition will want early, reliable visibility into exactly which shareholders might need to be brought into the transaction under a tag-along right, information that directly affects deal structuring, timeline, and the ultimate purchase price negotiation.
The cost of getting this tracking wrong tends to surface at the worst possible moment: during live deal negotiations, when a buyer’s diligence team identifies a tag-along right the selling shareholder’s own advisors had not accounted for, forcing a last-minute renegotiation of deal structure, price, or timeline. Maintaining a simple, current register of every tag-along right, who holds it, what threshold triggers it, and whether it has been properly incorporated into the articles, is a relatively low-effort step that substantially reduces the risk of this kind of disruptive surprise.
Call to Action: Where Can You Learn More?
Clauses like this one don’t sit in isolation, they sit inside a much larger body of corporate and commercial law. If you want a structured, foundational understanding of how Indian company law shapes the contracts, governance, and compliance work you do every day, LeDroit India’s Company Laws in India Certificate Course is a good next step.